If you’re searching for foreclosure help in Charlotte, NC, you still have options. North Carolina lenders must wait 45 days after a “breach” letter and at least 120 days of missed payments before a foreclosure hearing can even be scheduled. Use that breathing room to choose the best path forward.
Table of Contents
-
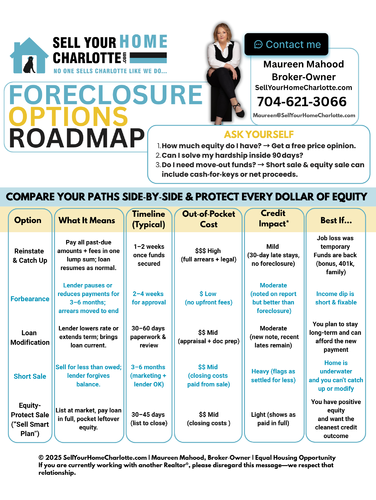
Reinstate the Loan
-
Modify the Loan
-
Sell Smart
-
Free “Stay‑in‑Control” Toolkit
-
10‑Question FAQ
-
Next Steps
Reinstate the Loan: Catch Up & Move On
Stops foreclosure instantly. Wire the past‑due amount plus late fees and the case disappears.
-
No extra paperwork. Your rate and term stay the same.
-
You keep every dollar of equity.
Quick Tip: Skip the main menu—call your servicer’s loss‑mitigation line and ask for a written reinstatement quote with a deadline. If the lump sum feels impossible, jump to Option 2 or dial the free State Home Foreclosure Prevention Project at 888‑442‑8188.
Modify the Loan: Lower or Stretch the Payment
A loan mod can roll missed payments to the back of the loan, drop your rate, or extend the term.
-
Lenders prefer mods over auctions—it costs them less.
-
Paperwork is simple: hardship letter, pay stubs, bank statements, last tax return, and a budget proving the new payment works.
Heads‑Up: Send a complete package; missing docs reset the 30‑day review clock. Park any “trial” payments in a separate account until you get written approval.
Sell Smart: Cash Out on Your Timeline
When keeping the house no longer fits your life or budget, listing before the courthouse auction lets you:
-
Protect credit. A standard sale reports paid‑off, not foreclosed.
-
Pick your closing date. Need 60 days to move? Add it to the contract.
-
Walk away with cash. Charlotte prices remain up year‑over‑year, so most sellers leave with money in hand—even after clearing arrears.
How I Deliver Fast, Top‑Dollar Sales
|
Guide
|
Why It Matters
|
|---|---|
|
72‑Hour Prep Mini‑Guide
|
Declutter, patch, and stage in three days for scroll‑stopping photos.
|
|
Sell Fast vs. Short Sale Net Sheet
|
Plug in value, payoff, and arrears—see which path leaves more cash with you.
|
|
15‑Point Sell‑Smart Plan
|
Step‑by‑step marketing that drives offers under a deadline.
|
|
30‑Day Action Plan
|
Daily checklist to stay ahead of bank timelines.
|
|
How to Spot Foreclosure‑Rescue Scams
|
Five red‑flag phrases that scream “walk away.”
|
FAQs
|
#
|
Question
|
Quick Answer
|
|
1
|
How long after an auction notice can I reinstate?
|
Up to 5 p.m. the day before the sale; the notice must post 20 days and publish 2 weeks.
|
|
2
|
What is the 10‑day upset‑bid period?
|
Anyone may out‑bid the buyer within 10 days, which can buy you more time to reinstate or sell.
|
|
3
|
Will I owe the bank if the sale price is short?
|
Possibly—NC allows deficiency judgments, but listing early usually avoids them.
|
|
4
|
Can I stay during a mod review?
|
Yes, once the lender marks your package “complete,” foreclosure is paused.
|
|
5
|
How do I spot a foreclosure‑rescue scam?
|
Up‑front fees, deed transfers, or “guaranteed” stops are red flags—call HUD first.
|
|
6
|
What docs do lenders need for a mod?
|
Hardship letter, pay stubs, bank statements, tax return, and a realistic budget.
|
|
7
|
Short sale vs. equity sale—difference?
|
Short sale nets less than payoff and needs bank OK; equity sale closes like any listing.
|
|
8
|
When does a deed‑in‑lieu make sense?
|
Little/no equity and failed mod or short‑sale attempts.
|
|
9
|
Can bankruptcy stop foreclosure?
|
Chapter 13 triggers an automatic stay but requires on‑time future payments.
|
|
10
|
Who offers free help right now?
|
HUD‑approved counselors & the NC State Home Foreclosure Prevention Project (888‑442‑8188).
|
Foreclosure Guide
Sell it Fast – 30 day plan
Check out this article next